Skip to content

Yitz Stern

Investor reviewing tokenized fund holdings on a laptop with blockchain network graphics in the background

How Blockchain Technology is Transforming the Investment Landscape

Blockchain technology is changing investing by letting you hold, transfer, and settle ownership records as digital tokens, reducing manual reconciliation and enabling near real-time movement of “cash-like” and fund exposures across platforms. You get faster operational… 
Users managing finances on digital banking apps

The Future of Banking: A Look at the Top Digital-Only Banks

Digital-only banks are shaping the future of banking by eliminating physical branches, reducing structural costs, and delivering app-first financial control that aligns with how you actually manage money today. You gain faster access, clearer pricing,… 

Business team reviewing project dashboards on a large screen and laptop inside a modern workspace.

Top 5 Project Management Platforms for Scaling Your Business

You scale your business faster when you use project management platforms that strengthen accountability, sharpen execution, and streamline your team’s daily rhythm. The tools you choose directly influence your operational performance. This guide gives you… 

A professional analyzing AI productivity dashboards on a laptop showing automation workflows and task metrics.

The 7 Best AI Productivity Tools to Automate Your Workflow

AI productivity tools automate your workflow by handling repetitive tasks, organizing projects, and improving communication efficiency, allowing you to focus on high-impact decisions and creative problem-solving. Artificial intelligence has redefined how you manage time, projects,… 

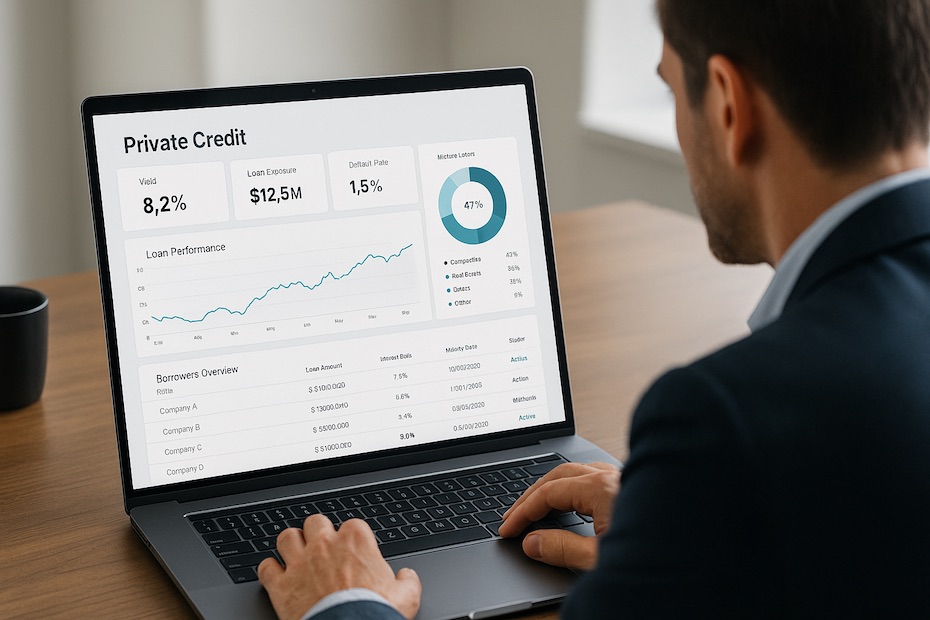
Private credit allows you to earn higher returns by lending directly to companies outside traditional banking and public bond markets. It offers attractive yields and portfolio diversification but requires careful assessment of liquidity and borrower risk. As an investor, you’re entering a space that’s rapidly gaining institutional momentum. This guide helps you understand private credit’s mechanics, identify opportunities, manage risks, and determine where it fits into your broader investment strategy. What Is Private Credit and Why It Matters to You Private credit, also known as private debt, refers to loans made to private companies that aren’t financed through public bond markets or banks. You effectively become the lender, earning interest income in exchange for taking on credit risk. Unlike traditional fixed-income securities that trade daily, private credit investments are negotiated directly between borrower and lender. This structure provides flexibility on terms, pricing, and collateral—but limits liquidity. In recent years, the asset class has exploded as regulatory changes reduced banks’ appetite for middle-market lending. That gap opened opportunities for investors seeking stable, high-yield income streams in a low-volatility environment. You benefit from the spread between what banks once earned and what borrowers are still willing to pay for credit. Why Investors Are Turning to Private Credit As yields in public bonds tightened, investors started moving toward private credit to capture higher risk-adjusted returns. Floating-rate structures also make it attractive in today’s higher interest-rate climate. Institutional data supports the trend. According to Preqin, global private credit assets surpassed $1.7 trillion in 2024, and demand continues to rise. Pension funds, insurance companies, and family offices have all expanded allocations as they search for steady cash flow and protection from public market swings. Private credit also offers portfolio diversification. It’s typically less correlated with equities, giving you stability during volatile markets. For many investors, it bridges the gap between equity-like returns and bond-like predictability—a rare balance in modern portfolios. When managed prudently, it can provide: Enhanced yield from non-bank loans and structured credit Reduced correlation with public equities and bonds Inflation resilience through floating-rate interest structures Capital preservation via senior-secured or collateralized positions Understanding the Core Types of Private Credit To allocate effectively, you must distinguish between the major private credit strategies—each with unique risk and return profiles. 1. Direct Lending: This is the backbone of private credit. You lend directly to mid-market companies that may not qualify for large bank loans. Loans are often senior-secured, giving you priority in repayment. 2. Mezzanine Debt: You provide subordinated financing that ranks below senior loans but above equity. It typically includes higher interest rates and sometimes equity warrants for upside potential. 3. Distressed Debt: You buy debt from struggling companies at a discount, aiming for gains if they recover or restructure. It requires experience in credit analysis and a tolerance for higher risk. 4. Specialty Finance: This covers niche markets such as equipment leasing, trade finance, or consumer loans. Returns vary, but these strategies often deliver steady cash flow with shorter durations. 5. Real Estate Debt: You lend against property-backed assets, earning interest and potentially benefiting from asset appreciation. It’s popular among investors seeking collateralized exposure to the property market. Understanding where each fits helps you align strategy with your risk appetite and liquidity needs. How Private Credit Generates Returns Your returns in private credit primarily come from interest income and occasionally fees or equity kickers. The appeal lies in its yield premium over public bonds. Since the loans aren’t traded, you earn a liquidity premium—compensation for tying up capital for several years. Borrowers often pay higher spreads because private credit offers flexibility that banks cannot match. Moreover, most private credit instruments use floating interest rates, which adjust with benchmarks like SOFR. This shields you from the negative effects of rising rates, a key advantage over fixed-rate bonds. However, performance depends heavily on disciplined underwriting. Strong covenants, collateral protection, and conservative leverage ratios are what separate sustainable returns from unnecessary risk. What Risks You Must Manage Before Investing Every high-yield asset carries trade-offs. Private credit isn’t immune to risk—it just packages it differently. Credit Risk: Borrowers are often smaller, non-investment-grade firms. You must assess their ability to service debt through cash flow, collateral, and business fundamentals. Liquidity Risk: Most private credit vehicles restrict withdrawals for several years. Once invested, you can’t easily exit before maturity. Manager Risk: Because you invest through specialized funds, performance depends on the fund manager’s credit selection, underwriting skill, and risk control. Macroeconomic Risk: A tightening economy can trigger defaults, especially in cyclical industries. Monitoring credit spreads and economic indicators helps you anticipate potential drawdowns. You can mitigate these risks by: Choosing experienced managers with long-term track records Focusing on senior-secured loans backed by assets Diversifying across borrowers and industries Keeping allocation size aligned with your liquidity profile By approaching private credit with institutional discipline, you can capture its benefits while minimizing downside exposure. How to Access Private Credit as an Individual Investor Historically, private credit was accessible only to institutional players. Today, new fund structures and digital platforms are making it more approachable. You can invest through: Private credit funds run by established managers such as Blackstone, Ares, or Blue Owl Business Development Companies (BDCs) listed on public exchanges for more liquidity Online investment platforms that pool smaller contributions from accredited investors Interval funds offering semi-liquid exposure for longer-term investors When evaluating options, pay close attention to fees, lock-up periods, and redemption policies. Lower-cost structures may look appealing, but strong credit management is what ultimately drives consistent returns. How to Conduct Due Diligence Before Investing Due diligence separates successful investors from those taking blind risks. You’re not just investing in loans—you’re investing in the discipline of the manager overseeing them. Start by assessing the fund’s history and performance consistency. Look for multi-year data through different credit cycles. Review default rates, loss recoveries, and covenant enforcement. Next, study the portfolio composition. Is it diversified by borrower, sector, and geography? Overconcentration in one industry—say, real estate or energy—can magnify exposure during downturns. Lastly, review fund fee structures and alignment of interest. Managers who invest their own capital alongside clients typically manage risk more conservatively. A quick evaluation checklist: Manager track record and historical defaults Average yield and loan-to-value ratios Strength of loan covenants Diversification by borrower and region Transparency and reporting quality Fund liquidity terms and redemption rights Performing this analysis upfront protects you from unpleasant surprises later. How Private Credit Fits into a Diversified Portfolio Private credit isn’t an isolated asset—it’s a tool for optimizing yield and stability across your broader portfolio. For most investors, an allocation of 5–15% to private credit complements public bonds and equities. It delivers higher yield than investment-grade debt without the volatility of stocks. In balanced portfolios, it functions as an income enhancer and risk diversifier. Because returns are driven by contractual interest payments, performance remains more stable than equity-linked alternatives. You can tailor allocations by risk profile: Conservative investors may favor senior-secured or real estate debt Moderate investors can blend direct lending with mezzanine exposure Aggressive investors may pursue opportunistic or distressed debt funds The key is maintaining proper liquidity planning—aligning lock-up durations with your investment horizon. Key takeaways on private credit investing Non-bank lending to private firms Higher yield, lower market correlation Illiquid, but income-focused and inflation-resistant Build Smarter Yield Strategies with Confidence Private credit gives you access to opportunities that once belonged exclusively to institutional investors. You now have tools to generate attractive returns while supporting real business growth outside the banking system. Investor analyzing private credit dashboard showing loan performance, borrower data, and yield metrics on a modern laptop.

An Investor’s Guide to Navigating the World of Private Credit

Private credit allows you to earn higher returns by lending directly to companies outside traditional banking and public bond markets. It offers attractive yields and portfolio diversification but requires careful assessment of liquidity and borrower…